
Appendix B - flowchart of accounting for changes in make good provision estimates
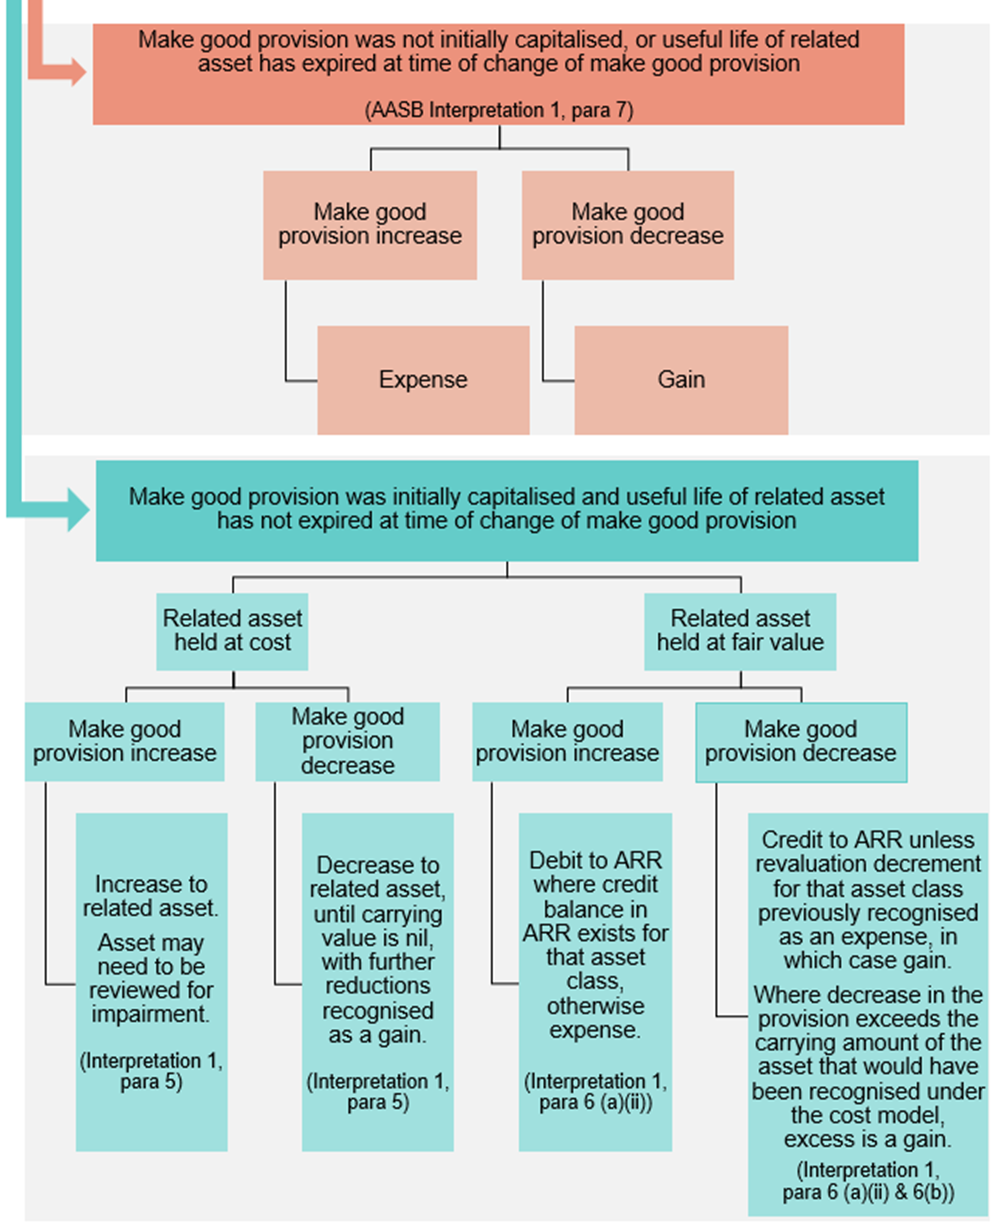
View the flowchart to determine the accounting treatment for changes in make good provision estimates.
Last updated: 22 September 2026
On this page
This flowchart summarises accounting for changes in make good provision estimates (under AASB Interpretation 1).
Change in make good provision estimates
Policies, legislation and guidelines
Link copiedTools and templates
Link copied- Interpretations
- Accounting Standards
- Appendix A - Illustrative examples
- Appendix B - flowchart of accounting for changes in make good provision estimates
- AASB 16 Leases
- AASB 116 Property, Plant and Equipment
- AASB 137 Provisions, Contingent Liabilities and Contingent Assets
- AASB Interpretation 1 Changes in existing decommissioning, restoration and similar liabilities
- RMG 110 Accounting for leases
Glossary
Link copiedAcronyms
- AASB - Australian Accounting Standards Board
- ARR - Asset revaluation reserve
- CBMS - Central Budget Management System
- FRR - Public Governance, Performance and Accountability (Financial Reporting) Rule 2015
- FV - Fair value
- OCI - Other comprehensive income
- PPE - Property, plant and equipment
- PV - Present value
- RMG - Resource management guide
- TVOM - Time value of money
Relevant sections of the PGPA Act and Rule
Link copiedPGPA Rule - section 17