
RMG 115 Accounting for concessional loans
On this page
RMGs are guidance documents. The purpose of an RMG is to support PGPA Act entities and companies in meeting the requirements of the PGPA framework. As guides, RMGs explain the legislation and policy requirements in plain English. RMGs support accountable authorities and officials to apply the intent of the framework. It is an official’s responsibility to ensure that Finance guidance is monitored regularly for updates, including changes in policy/requirements.
A concessional loan is a loan made on more favourable terms than the borrower could obtain in the market place.
A concessional loan provided by government basically has two embedded components; a ‘market-based loan’ as well as a ‘concessional loan’ component. The concessional component represents the opportunity cost that the government has forgone by providing the loan at a discounted rate (AASB 9: Financial Instruments (AASB 9) paragraphs 5.1.1 and B5.1.2A(a)).
Entities that make concessional loans are to calculate the fair value of the loan by using a valuation technique, such as by discounting all future cash receipts at the prevailing market interest rate for a similar financial asset.
Audience
Link copiedThis resource management guide (RMG) applies to officials in Commonwealth entities that issue concessional loans, including accountable authorities, chief financial officers and finance teams.
Key points
Link copiedThe scope of this RMG is Commonwealth entity accounting requirements for concessional loans. Content in this guide on the ‘market-based loan’ components is also relevant to other financial instruments measured at amortised cost or at fair value.
This RMG provides guidance on accounting for concessional loans including:
- discounting using the effective interest method (EIM)
- the unwinding of the discount
- relevant Central Budget Management System (CBMS) accounts
- illustrative examples of journal entries.
While the guide includes some basic examples, it is not intended to address all the complexities that may arise. Entity’s proposed approaches should be agreed with relevant audit teams in those instances.
Part 1 – Accounting on initial recognition
Link copiedA concessional loan provided by the government is a combination of a market-based loan with a concessional component that may include:
- interest rate discounts
- longer loan maturity
- grace periods before payments of principal or interest are required.
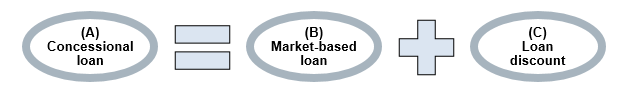
The value of a concessional loan is comprised of the market-based loan plus the loan discount component.
Concessional loan = market based loan + loan discount
Figure 1: Calculating the value of a concessional loan
Initial recognition of concessional loans depends on:
- how the loan is classified under AASB 9
- whether a commitment to issue the concessional loan precedes provision of the loan
- for simplicity, unless otherwise specified, commitments to issue concessional loans are assumed to have occurred when the loan funds were provided. However recognition of a liability may be required where there is an extended lag between the inception of the loan and payment of loan funds.
Loan classification
- Under AASB 9, financial assets (such as concessional loans) are classified as:
- measured at amortised cost—where:
- they are usually held only to collect contractual cash flows
- the contractual terms only provide payments on specified dates that are solely payments of principal and interest (SPPI test) (AASB 9 paragraph 4.1.2).
- measured at amortised cost—where:
measured at fair value through other comprehensive income (FVOCI)—where:
they are held both to collect contractual cash flows and to sell financial assets; and
the contractual terms only provide payments on specified dates of principal and interest (AASB 9 paragraph 4.1.2A)
measured at fair value through profit or loss (FVPL)—where they do not meet the classification criteria for either held at amortised cost or FVOCI (AASB 9 paragraph 4.1.4).
Concessional loans generally meet the criteria for classification as financial assets measured at amortised cost. An exception is Commonwealth concessional loans where repayments are income contingent (eg the Higher Education Loan Program (HELP)). These loans are assessed as not meeting the SPPI criteria and hence are classified as FVPL (AASB 9 paragraphs B4.1.7A and B4.1.13).
AASB 9 Paragraphs 4.1.5 and 4.2.2 allow entities to designate financial assets and liabilities on initial recognition as measured at FVPL where it reduces or removes a measurement inconsistency.
Initial recognition and measurement
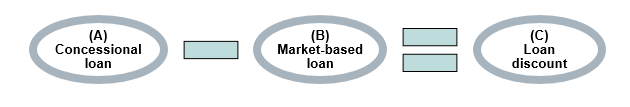
On initial recognition, the market-based loan and the loan discount components that make-up the concessional loan are separated. The difference between the loan’s nominal value at the concessional rate and fair value at the market rate represents the discount implicit in the loan.
Concessional loan - market-based loan = loan discount
Figure 2: Calculating the loan discount
The discount component of the concessional loan is immediately recognised as an expense when the entity has a contractual commitment to provide a loan at a below-market interest rate. Measurement of the initial concessional loan discount expense does not depend on how the loan is categorised under AASB 9.
CBMS manages the flow of financial information between Finance and Commonwealth Government entities to facilitate cash and appropriation management, preparation of budget documentation and financial reporting. The relevant CBMS account and account descriptors are provided in the table below.
Table 1: Journal entries for recognition of a concessional loan
| Dr/Cr | CBMS account | CBMS account description |
|---|---|---|
| Dr | 2423001 | Concessional loan discount (expense) |
| Dr | 5232102 | Other loans and advances – Advances and loans made |
| Cr | 5232104 | Other loans and advances – Non cash movements |
| Cr | 5220002 | Cash at bank |
The market-based loan is recognised as a financial asset (advances and loans made) on the balance sheet and measured under AASB 9 paragraph 5.1.1 as follows:
- if the loan is categorised as measured at amortised cost or FVOCI, the amount recognised on initial recognition is the fair value of the loan plus transaction costs
- if the loan is categorised as FVPL, the amount recognised on initial recognition will only include the fair value of the loan. Transaction costs will be expensed immediately on recognition.
Fair value
The fair value of a concessional loan will usually not be its transaction price1. The fair value of concessional loans should be calculated by using a valuation technique (e.g. by discounting all future cash receipts at the prevailing market interest rate for a similar financial asset using discounted cash flow (DCF) analysis2). Estimation of prevailing market interest rates may require review of publicly available commercial loan information or independent valuation advice.
For more information regarding the use of fair value measurement valuation techniques see AASB 13: Fair Value Measurement (AASB 13).
Illustrative example of the discount rate for calculating fair value
A company with a ‘B’ credit rating receives a $5 million loan from the government, for a 10-year term, at a concessional interest rate of 3% per annum. The applicable interest rate for companies with a similar credit rating and for a similar project, loan amount and term would have been 8% per annum. Consequently, the discount rate for the DCF calculation of fair value is 8% per annum.
1 If the loan is repayable on demand, the concessional loan discount expense is zero.
2 This technique falls under the ‘income approach’ for AASB 13.
Part 2 – Accounting after initial recognition
Link copiedLoans held at amortised cost
The amortised cost of the market-based loan can be calculated as follows:
- Carrying amount of loan at initial recognition
- Add: Interest income accrued using the EIM
- Less: Principal and interest payments (cash flows)
- Equals: Gross carrying amount
- Less: Expected credit loss allowance (ECLA)
- Equals: Amortised cost
Accounting for concessional loans measured at amortised cost depends on whether the loan’s credit risks have increased significantly since the loan was initially recognised, or the loan has become credit impaired. AASB 9 Appendix A defines ‘credit-impaired’ as financial assets for which adverse events have already occurred which significantly increase the asset’s credit risks, such as loan defaults or general financial difficulties of the borrower.
Step (a): Carrying amount of loan on initial recognition
On initial recognition, the market-based loan was recognised at fair value plus transaction costs, as outlined above.
Step (b): Interest income using the EIM
The EIM is a method of calculating the amortised cost of a financial asset and allocating the interest income over the relevant period using the effective interest rate (EIR).
For loans that have not become credit impaired, the EIR is the rate that exactly discounts contracted future principal and interest receipts through the expected life of the concessional loan back to the loan’s gross carrying amount. The loan’s gross carrying amount is its amortised cost but before deduction of the ECLA (see AASB 9 Appendix A and paragraph 5.4.1). Future principal and interest receipts should not be adjusted for expected credit losses.
The EIR is usually the market interest rate used to calculate the loan’s fair value. However, where directly attributable transaction costs have been capitalised, the EIR will be lower than the relevant market interest rate in order to equate the loans carrying value at initial recognition with the present value of future principal and interest repayments.
For loans that have become credit impaired, the EIR should be applied to the amortised cost of the loan (gross carrying amount of the financial asset after deducting the ECLA).
Income calculated using the EIM can be separated into two components:
- interest income received
- unwinding of the discount.
Table 1 provides a template for calculating the unwinding of loan discount expense and the unexpired discount. Appendix A provides illustrative examples, including completed examples of this table.
Table 2: Template for calculating unwinding of discount and unexpired discount
|
Year |
(a) Opening loan discount |
(b) Income |
(c) Interest |
(d) = (b) – (c) Income from unwinding of discount |
(e) = (a) – (d) Unexpired |
|---|---|---|---|---|---|
| 1 | |||||
| 2 |
The unwinding of the discount (d) is the difference between interest income calculated under the EIM (b) and the interest income calculated using the loan’s contract interest rate (c). The unwinding of the loan discount component, which was expensed on initial recognition over the life of the loan, is treated as a revenue. CBMS account and account descriptors for unwinding a concessional loan are:
Table 3: Journal entries for recognition of a concessional loan
| Dr/Cr | CBMS Account | CBMS account description |
|---|---|---|
| Dr | 5232104 | Other loans and advances – Non cash movements |
| Cr | 1234001 | Unwind concessional loan discount (income) |
Examples are provided at Appendix A of the application of the EIR to loans that:
- have not become credit impaired (Scenarios: A.1 to A.4)
- have become credit impaired (Scenario A.5).
Step (c): Gross carrying amount
The gross carrying amount of financial assets measured at amortised cost (before ECLA) can be presented in an amortisation schedule. Table 2 provides a template for preparing an amortisation schedule for a market-based loan. Appendix A provides illustrative examples, including completed examples of this table.
Table 4: Template for preparing an amortisation schedule – market-based loan
|
Year |
(a) Opening gross carrying amount |
(b) = (a) x EIR Income (using EIM) |
(c) Cash flows |
(d) = (a) + (b) – (c) Closing gross carrying amount |
|
|---|---|---|---|---|---|
| 1 | |||||
| 2 |
Step (d): ECLA
Concessional loans classified as measured at amortised cost will also need to be reduced by an ECLA as follows:
- Where there has not been a significant increase in credit risk since initial recognition, the ECLA should reflect the present value of estimated cash shortfalls over the life of the loan, from default events expected to occur over the next year only (see AASB 9 paragraphs 5.5.5 and 5.5.17).
- Where there has been a significant increase in credit risk since initial recognition, or the loans have become credit impaired, the ECLA should reflect the present value of estimated cash shortfalls from default events occurring over the life of the loan (see AASB 9 paragraph 5.5.3 and 5.5.17).
Significant increases in credit risk reflects an increase in the default risk profile over the life of the loan, without the loan already becoming impaired. Significant increases in credit risk are not based on the change in expected credit losses (AASB 9 paragraph 5.5.9). Consequently, the amount of collateral should not be considered.
Entities need to determine their own accounting policy and recording procedures for determining for each loan whether significant increases in credit risk have occurred since initial recognition. However, AASB 9 provides the following guidance:
- Entities can assume that credit risk has not increased significantly since initial recognition where a loan has low credit risk at reporting date (AASB 9 paragraph 5.5.10)
- Entities should generally presume that credit risk has increased significantly since initial recognition where payments are more than 30 days past due (AASB 9 paragraphs 5.5.11 and B5.5.19).
Assessments of significant increases in credit risk may need to incorporate estimates of multiple variables, such as forecast changes in business profitability, general macroeconomic conditions, changes in applicable market credit spreads and changes in internal or external credit ratings. Loan portfolios may need to be assessed collectively in conjunction with loan specific parameters (overdue ageing).
- loans may be grouped on the basis of shared credit risk characteristics, such as loan type, borrower type, industry, geographic location (AASB 9 paragraph B5.5.16).
- consistent credit risk assessments on initial recognition for each loan group would facilitate identification of subsequent changes in credit risk (assessment of changes in credit risk are relative to assessments on initial recognition, so assessment of loans to the same borrower may differ depending on when the loans were initially recognised).
IFRS 9 Illustrative Examples 5 to 7 provides further guidance on collective assessment of borrower credit risks.
AASB 9 does not specifically define default. AASB 9 paragraph B5.5.37 states that entities should apply a definition consistent with their internal credit risk management practices, but should generally assume that any loans 90 or more days overdue have defaulted.
ECLA’s are the probability weighted estimate of possible cash receipt shortfalls over the life of the loan (probability of default multiplied by loss given default (LGD)), discounted back to present value as at reporting date using the EIR (AASB 9 paragraphs 5.5.17 and B5.5.28). LGD should be net of expected collateral recoveries. ECLA may also be estimated collectively, based on historical credit loss data (eg matrix of loss probabilities by past due ageing categories) adjusted for forward information where available (AASB 9 paragraph B5.5.52).
Because the ECLA reflects estimated cash shortfalls discounted by the EIR, the ECLA will always be a portion of the loans gross carrying amount (after concessional loan discount expense). The ECLA should be revised at each reporting date, including for the unwinding of the present value of estimated cash receipt shortfalls, with any movement posted to the Income Statement (AASB 9 paragraph 5.5.8), as shown below. Recognition of ECLA is treated as an ‘Other Economic Flows’ for Government Finance Statistics (GFS) purposes and has no impact on fiscal balance.
Table 5: Journal entries for recognition of ECLA
| Dr/Cr | CBMS account | CBMS account description |
|---|---|---|
| Dr | 2251004 | Loans and Advances Bad Doubtful Debts |
| Cr | 5233023 | Provision for Doubtful Debts - Other |
Debt write offs should be deducted from both the loan receivable and the ECLA when the loan is not expected to be recovered, as shown below. Debt write offs also do not impact the fiscal or underlying cash balances.
Table 6: Journal entries to reflect debt write off
| Dr/Cr | CBMS account | CBMS account description |
|---|---|---|
| Dr | 5233023 | Provision for Doubtful Debts - Other |
| Cr | 5232104 | Other loans and advances – Non cash movements |
Debt waivers however are treated as economic transactions for GFS purposes, worsening the fiscal balance. Where waivers occur, the expense should be re-classified as follows.
Table 7: Journal entries to reflect debt waiver
| Dr/Cr | CBMS account | CBMS account description |
|---|---|---|
| Dr | 2251090 | Remissions – Loans and Receivables |
| Cr | 2251004 | Loans and Advances Bad Doubtful Debts |
Appendix B provides a detailed example of the calculation of an ECLA as at loan commencement. AASB 9 paragraphs B5.5.1 to B5.5.55 and IFRS 9 Illustrative Examples 8, 9 and 12 also provide more guidance on ECLAs. In general, agencies should agree proposed approaches with their audit team.
Fair value through profit or loss loans
Loans classified at FVPL should be remeasured to fair value at each reporting date, with any adjustment recognised as an expense or gain. No ECLA should be recognised on loans measured at FVPL (AASB 9 paragraph 5.5.1).
Part 3 – Loan commitments
Link copiedAccounting for concessional loans may be further complicated where the commitment to issue the loan materially precedes the provision of loan funds. AASB 9 paragraph 4.2.1(d) requires that commitments to provide a loan at a below-market interest rate should be recognised as a liability and measured at the higher of:
- the provision for ECLA
- the fair value of the financial liability.
AASB 9 Appendix A defines a firm commitment as a “binding agreement for the exchange of a specified quantity of resources at a specified price on a specified future date or dates”. Therefore, a loan commitment would only be recognised as a liability where the loan documentation has been signed by all parties and the Commonwealth becomes legally bound to provide the loan.
The fair value of the loan commitment liability would usually be its estimated fair value when funds are issued, discounted back to the date of contractual commitment using the entity’s normal discount rate.
The ECLA on loan commitments would be the present value of the estimated cash shortfalls that the Commonwealth may incur based on estimated loan drawdowns (AASB 9 paragraph B5.5.30). Estimated loan drawdowns should be for the 12 months after reporting date where estimating 12-month expected credit losses and should be over the expected life of the loan commitment when estimating lifetime expected credit losses (AASB 9 paragraph B5.5.31). Expected credit losses on a loan commitment should be discounted using the EIR (AASB 9 paragraph B5.5.47).
Paragraph B8E of AASB 7 Financial Instruments: Disclosures (AASB 7) states that loss allowances relating to undrawn loan commitments should be classified as provisions. AASB 9 paragraph 5.7.9 states that any change in the loan commitment liability up until the issuance of loan funds should be recognised in the Income Statement. Example A.7 in Appendix A provides further guidance on accounting for loan commitments.
Part 4 – Disclosure requirements
Link copiedFinancial instrument disclosure requirements are specified in AASB 7. AASB 13 also requires additional fair value measurement disclosures (subject to paragraph 29 of AASB 7).
Table 8: Budget implications
| Transaction | Fiscal balance/net operating balance | Underlying cash balance |
|---|---|---|
| Initial recognition - loan component | Nil impact (no impact on net operating balance or on net acquisitions of non-financial assets) |
Nil impact (loan component treated as an investment in financial assets cash outflow not an operating outflow) |
| Initial recognition - discount component | Worsen (discount expense reduces net operating balance) |
Nil impact (no cash inflow/outflow) |
| Principal repayment | Nil impact (no impact on net operating balance or on net acquisitions of non-financial assets) |
Nil impact (principal repayment is treated as an investment in financial assets cash inflow) |
| Cash interest received (interest income) | Improve (interest income increases revenue) |
Improve (interest cash inflow (receipts) treated as an operating cash inflow) |
| Unwinding of discount component | Improve (treated as interest income, increasing revenue) |
Nil impact (no cash inflow/outflow) |
| ECLA adjustments |
Nil impact (no impact on net operating balance or on net acquisitions of non-financial assets) |
Nil impact (no cash inflow/outflow) |
| Debt write offs |
Nil impact (no impact on net operating balance or on net acquisitions of non-financial assets) |
Nil impact (no cash inflow/outflow) |
| Agreed debt waivers | Worsen (debt remissions reduce net operating balance) |
Nil impact (no cash inflow/outflow) |
Appendix 1 – Illustrative examples
Link copiedThe appendix provides illustrative examples for accounting for various concessional loan scenarios, including:
A.1 – Below market-rate loan
A.2 – Interest free loan
A.3 – Below market-rate loan with grace period
A.4 – Interest-free loan with grace period
A.5 – Credit impaired interest-free loan
A.6 – Interest-free loan where repayment is income contingent
A.7 – Forward-year concessional loan
For simplicity, A.1 to A.7 are basic examples. Some further complexities relating to loans measured at amortised cost may be:
- loans may be issued in successive instalments, rather than in a single amount. In this case, it may be necessary to account for each instalment as a separate loan. In particular, estimation of the ECLA requires assessment of the change in credit risk since initial recognition
- where loans are issued at a variable rather than fixed interest rate. Where changes in interest receipts due to changes in a floating interest rate are material, the gross carrying amount of the loan should be recalculated using the original EIR, with the adjustment recognised in the Income Statement (AASB 9 paragraph B5.4.6)
- loan terms may be modified (eg several years after initial recognition): Judgement may be required to determine if the modifications are so significant that the original loan should be de-recognised and a new loan recognised. If the original loan is not de-recognised, paragraph 5.4.3 of AASB 9 states that the gross carrying amount of the loan should be recalculated, using the original EIR, with any adjustment recognised as a modification gain or loss. The ECLA should also be recalculated, based on whether credit risks have increased significantly since initial recognition.
Agreement of the proposed approach with the audit team is recommended in these instances.
A.1 – Below market-rate loan
Scenario
On 1 July 20X0, the lending entity agrees to provide a loan on the following terms:
- Principal: $700,000
- Term: 4 years
- Loan interest rate: 3.45 per cent per annum
- Repayments: to be repaid evenly over the loan term ($175,000 per annum).
Other factors/considerations:
- Loan documents: signed at the date of the loan funds being provided.
- Market-rate: if the loan was borrowed in the market place, the borrowing would have been subject to an interest rate of 7.45 per cent per annum.
- Transaction costs: no transaction costs directly attributable to the issue of the concessional loan were incurred.
- Loan interest: calculated on the amount outstanding at the beginning of the year. Cash flows occur at year-end.
- Credit risks: assessed over the life of the loan to have not significantly increased since initial recognition.
Expected credit losses estimated at the beginning of each financial year, based on the weighted probability of default occurring in the next 12 months, are shown in Table A.1.1.
Table A.1.1: Expected credit loss allowance (ECLA)
| Year | Principal outstanding | Expected credit loss allowance |
|---|---|---|
| July 20X0 | $700,000 | $50,000 3 |
| July 20X1 | $525,000 | $32,000 |
| July 20X2 | $350,000 | $12,000 |
| July 20X3 | $175,000 | $4,000 |
3 An example calculation of ECLA is shown at Appendix B.
Accounting guidance
Entity A should classify the loan as a financial asset measured at amortised cost as it is only held to collect contractual cash flows and contractual cash flows are solely payments of principal and interest on specified dates.
As the loan agreement was finalised at the date the loan funds were provided, no loan commitment needs to be initially recognised.
For this scenario, the entity will need to account for:
- Discounted cash flow analysis
- Amortisation schedule – market-based loan
- Calculation of unwinding of discount and unexpired discount
- Reconciliation of the expected credit loss allowance.
The entity separates the concessional loan (A) into its component parts:
- a market-based loan (B)
- the discount component (C).
Concessional loan (A) = market based loan (B) + loan discount (C)
Discounted cash flow analysis
The market-based loan (B) is recognised at fair value using discounted cash flow (DCF) analysis as follows:
PV of future cash flows = ∑Cash flows / (1 + discount rate) Time period
Where:
- cash flows are the cash receipts for the period (principal and interest repayments)
- the discount rate is the prevailing market rate of interest for a similar instrument
- the time period is the number of years over which the PV calculation is performed.
Table A.1.2: Discounted cash flow analysis
| Year | Principal repayment | Interest payment at loan rate (3.45%) | Total cash flows |
PV at loan rate (A) |
PV at market rate (B) |
|---|---|---|---|---|---|
| 20X0-X1 | $175,000 | $24,150 (700,000 x 0.0345) |
$199,150 | $192,508 (199,150 / (1.0345)1) |
$185,342 (199,150 / (1.0745)1) |
| 20X1-X2 | $175,000 | $18,113 (525,000 x 0.0345) |
$193,113 | $180,447 (193,113 / (1.0345)2) |
$167,263 (193,113 / (1.0745)2) |
| 20X2-X3 | $175,000 | $12,075 (350,000 x 0.0345) |
$187,075 | $168,976 (187,075 / (1.0345)3) |
$150,798 (187,075 / (1.0745)3) |
| 20X3-X4 | $175,000 | $6,038 (175,000 x 0.0345) |
$181,038 | $158,069 (181,038 / (1.0345)4) |
$135,814 (181,038 / (1.0745)4) |
| Total | $700,000 | $60,376 | $760,376 | $700,000 | $639,216 |
Calculating loan discount
The difference between the loan’s nominal value at the concessional rate (A) and fair value at the market rate (B) represents the discount implicit in the loan (C).
Concessional loan (A) - market-based loan (B) = loan discount (C)
From information in Table A.1.2:
(Total column A) $700,000 – (Total column B) $639,216 = Loan discount (C) $60,784
Journal entries
At 1 July 20X0, the entity posts the following journals to recognise:
- fair value of the market-based loan component and expense the associated loan discount component
- an initial ECLA.
Table A1.2.1: Recognition of concessional loan
| Dr/Cr | CBMS Account | CBMS Account Description | Amount |
|---|---|---|---|
| Dr | 2423001 | Concessional loan discount (expense) | $60,784 |
| Dr | 5232102 | Other loans and advances – Advances and loans made | $700,000 |
| Cr | 5232104 | Other loans and advances – Non cash movements | $60,784 |
| Cr | 5220002 | Cash at bank | $700,000 |
Table A1.2.2: Recognition of ECLA
| Dr/Cr | CBMS Account | CBMS Account Description | Amount |
|---|---|---|---|
| Dr | 2251004 | Loans and Advances Bad Doubtful Debts | $50,000 |
| Cr | 5233023 | Provision for Doubtful Debts - Other | $50,0004 |
4 Refer to Appendix B for the derivation of the ECLA
Amortisation schedule – market-based loan
The following schedule outlines the amortisation of the market-based loan, and illustrates how the EIM effectively discounts estimated future principal and interest receipts through the expected life of the loan:
Table A.1.3: Amortisation schedule – market-based loan
|
Year |
(a) Opening gross carrying amount |
(b) = (a) x EIR Income (using EIM) |
(c) Cash flows5 |
(d) = (a) + (b) – (c) Closing gross |
|---|---|---|---|---|
| 20X0-X1 | $639,2166 | $47,622 | $199,150 | $487,688 |
| 20X1-X2 | $487,688 | $36,333 | $193,113 | $330,908 |
| 20X2-X3 | $330,908 | $24,653 | $187,075 | $168,486 |
| 20X3-X4 | $168,486 | $12,552 | $181,038 | $- |
5 Cash flows are from Table A.1.2: Discounted cash flow analysis
6 The total for (B) in Table A.1.2: Discounted cash flow analysis.
Calculation of unwinding of discount and unexpired discount
The following table illustrates the unwinding of the loan discount, which is calculated as the difference between the loan discount on initial recognition and any subsequent unwinding (writing back) of the discount component:
Table A.1.4: Calculation of unwinding of discount and unexpired discount
|
Year |
(a) Opening loan discount |
(b) Income (using EIM)7 |
(c) Interest income8 |
(d) = (b) – (c) Income from unwinding of discount |
(e) = (a) – (d) Unexpired loan discount at year end |
|---|---|---|---|---|---|
| 20X0-X1 | $60,7849 | $47,622 | $24,150 | $23,472 | $37,312 |
| 20X1-X2 | $37,312 | $36,333 | $18,113 | $18,220 | $19,092 |
| 20X2-X3 | $19,092 | $24,653 | $12,075 | $12,578 | $6,514 |
| 20X3-X4 | $6,514 | $12,552 | $6,038 | $6,514 | $- |
| Total | $121,160 | $60,376 | $60,784 |
7 Income from column ‘(b)’ in Table A.1.3: Amortisation Schedule.
8 Interest payments from Table A.1.2: Discounted cash flow analysis
9 As calculated using the ‘loan discount’ formula.
Reconciliation expected credit loss allowance
Table A.1.5: Reconciliation of expected credit loss allowance
| Year | Opening ECLA | Movement in ECLA | Closing ECLA |
|---|---|---|---|
| 20X0-X1 | $50,000 | $18,000 | $32,000 |
| 20X1-X2 | $32,000 | $20,000 | $12,000 |
| 20X2-X3 | $12,000 | $8,000 | $4,000 |
| 20X3-X4 | $4,000 | $4,000 | $0 |
Decrease in ECLA reflects reduction in credit risks over loan term.
Subsequent accounting
The lending entity posts the following journals at the end of each financial year:
Table A.1.5.1: Recognition of principal repayments ($175,000 per annum)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
|---|---|---|---|---|---|---|
| Dr | 5220002 | Cash at bank | 175,000 | 175,000 | 175,000 | 175,000 |
| Cr | 5232103 | Other loans and advances - Repayments | 175,000 | 175,000 | 175,000 | 175,000 |
Table A.1.5.2: Recognition of interest income (Table A.1.4 column ‘(c)’)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
|---|---|---|---|---|---|---|
| Dr | 5220002 | Cash at bank | 175,000 | 175,000 | 175,000 | 175,000 |
| Cr | 5232103 | Other loans and advances - Repayments | 175,000 | 175,000 | 175,000 | 175,000 |
Table A1.5.3: Recognition of the unwinding of the discount (Table A.1.4 column ‘(d)’)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
|---|---|---|---|---|---|---|
| Dr | 5232104 | Other loans and advances – Non cash movements | 23,472 | 18,220 | 12,578 | 6,514 |
| Cr | 1234001 | Unwind concessional loan discount (income) | 23,472 | 18,220 | 12,578 | 6,514 |
Table A.1.5.3: Recognition of the annual adjustment to expected credit loss allowance
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
|---|---|---|---|---|---|---|
| Dr | 5232104 | Other loans and advances – Non cash movements | 23,472 | 18,220 | 12,578 | 6,514 |
| Cr | 1234001 | Unwind concessional loan discount (income) | 23,472 | 18,220 | 12,578 | 6,514 |
A.2 – Interest free loan with initial transaction costs
Scenario
On 1 July 20X0, the lending entity agrees to provide the borrowing entity with an interest-free loan. The terms of the loan are as follows:
- Principal: $700,000
- Term: 4 years
- Loan interest rate: interest free
- Repayments: to be repaid evenly over the loan term ($175,000 per annum).
Other factors/considerations:
- Loan documents: signed at the date the loan funds were provided
- Market-rate: if the loan was borrowed in the market place, the borrowing would have been subject to an interest rate of 7.45 per cent per annum
- Transaction costs: directly attributable to issue of the concessional loan of $6,000 were incurred
- Credit risk: assessed over the life of the loan to have not significantly increased since the financial asset’s initial recognition.
Expected credit losses were estimated at the beginning of each financial year based on the probability of default occurring in the next 12 months.
Table A.2.1: Expected credit loss allowance (ECLA)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
|---|---|---|---|---|---|---|
| Dr | 5233023 | Provision for Doubtful Debts - Other | 18,000 | 20,000 | 8,000 | 4,000 |
| Cr | 2251004 | Loans and Advances Bad Doubtful Debts | 18,000 | 20,000 | 8,000 | 4,000 |
10 The calculation of ECLA is shown at Appendix B.
Accounting guidance
Concessional loan (A) = market based loan (B) + loan discount (C)
As per example A.1, the loan (A) is classified as a financial asset measured at amortised cost and no loan commitment needs to be initially recognised. The loan is separated into a market-based loan (B) and the loan discount (C).
Discounted cash flow analysis
The market-based loan (B) is recognised at fair value using DCF analysis. However, in this case, the cash receipts for the period only consist of the principal repayments as the concessional loan is interest free.
The EIR is 7.00 per cent per annum (even though the market rate is 7.45 per cent per annum) as it is the rate that discounts the contracted future principal and interest receipts through the expected life of the concessional loan back to the loan’s initial gross carrying amount (including capitalised transaction costs).
The PV of the future cash flows at the concessional rate of 0 per cent (column A) and at the market rate (column B) are illustrated in the following table:
Table A.2.2: Discounted cash flow analysis
| Year | Principal repayment | Interest payment at loan rate (0%) |
Total cash flows |
PV at loan rate (0%) (A) |
PV at market rate (7.45%) (B) |
|---|---|---|---|---|---|
| 20X0-X1 | $175,000 | $- | $175,000 | $175,000 (175,000 / (1.0000)1) |
$162,866 (175,000 / (1.0745)1) |
| 20X1-X2 | $175,000 | $- | $175,000 | $175,000 (175,000 / (1.0000)2) |
$151,574 (175,000 / (1.0745)2) |
| 20X2-X3 | $175,000 | $- | $175,000 | $175,000 (175,000 / (1.0000)3) |
$141,065 (175,000 / (1.0745)3) |
| 20X3-X4 | $175,000 | $- | $175,000 | $175,000 (175,000 / (1.0000)4) |
$131,284 (175,000 / (1.0745)4) |
| Total | $700,000 | $- | $700,000 | $700,000 | $586,790 |
Calculating loan discount
In this scenario, the difference between the interest free loan (A) and market-based loan (B) (before transaction costs) represents the discount implicit in the loan (C).
Concessional loan (A) - market-based loan (B) = loan discount (C)
From information in Table A.2.2:
(Total column A) $700,000 – (Total column B) $586,790 = Loan discount (C) $113,210
Journal entries
At 1 July 20X0, the lending entity posts the following journals to recognise:
- fair value of the market-based loan component (incorporating transaction costs of $6,000)
- an initial ECLA.
Table A.2.2.1: Recognise of the concessional loan at 1 July 20X0
| Dr/Cr | CBMS Account | CBMS Account Description | Amount |
|---|---|---|---|
| Dr | 2423001 | Concessional loan discount (expense) | $113,210 |
| Dr | 5232102 | Other loans and advances - Advances and loans made | $706,000 |
| Cr | 5232104 | Other loans and advances – Non cash movements | $113,210 |
| Cr | 5220002 | Cash at bank | $706,000 |
Table A.2.2.1: Recognition of ECLA on 1 July 20X0
| Dr/Cr | CBMS Account | CBMS Account Description | Amount |
|---|---|---|---|
| Dr | 2251004 | Loans and Advances Bad Doubtful Debts | $50,000 |
| Cr | 5233023 | Provision for Doubtful Debts - Other | $50,000 |
Amortisation schedule – market-based loan
The following schedule outlines the amortisation of the market-based loan, and illustrates how the EIM effectively discounts estimated future principal and interest receipts through the expected life of the loan.
Table A.2.3: Amortisation schedule – market-based loan
|
Year |
(a) Opening Gross Carrying Amount |
(b) = (a) x EIR Income (using EIM) |
(c) Cash flows11 |
(d) = (a) + (b) – (c) Closing Gross Carrying Amount |
|---|---|---|---|---|
| 20X0-X1 | $592,79012 | $41,493 | $175,000 | $459,285 |
| 20X1-X2 | $459,285 | $32,148 | $175,000 | $316,435 |
| 20X2-X3 | $316,435 | $22,148 | $175,000 | $163,585 |
| 20X3-X4 | $163,585 | $11,449 | $175,000 | $- |
11 Cash flows are from Table A.2.2: Discounted cash flow analysis.
12 The total for (B) in Table A.2.2: Discounted cash flow analysis, including directly attributable transaction costs of $6,000.
Calculation of unwinding of discount and unexpired discount
The following table illustrates the unwinding of the loan discount (noting that there may be discrepancies in totals due to interest rate rounding):
Table A.2.4: Calculation of the unwinding of discount and unexpired discount
|
Year |
(a) Opening loan discount |
(b) Income (using EIM)13 |
(c) Interest income14 |
(d) = (b) – (c) Income from unwinding of discount |
(e) = (a) – (d) Unexpired loan discount at year end |
|---|---|---|---|---|---|
| 20X0-X1 | $107,21015 | $41,493 | $- | $41,493 | $65,728 |
| 20X1-X2 | $65,728 | $32,148 | $- | $32,148 | $33,588 |
| 20X2-X3 | $33,588 | $22,148 | $- | $22,148 | $11,449 |
| 20X3-X4 | $11,449 | $11,449 | $- | $11,449 | $- |
| Total | $- | $107,210 |
13 Income from column ‘(b)’ in Table A.2.3: Amortisation Schedule.
14 Interest payments from Table A.2.2: Discounted cash flow analysis
15 Loan discount is net of directly attributable transaction costs of $6,000, as EIR has already been reduced from 7.45% to 7%.
Subsequent accounting
The lending entity posts the following journals at the end of each financial year:
Table A.2.4.1: Recognition of principal repayments ($175,000 per annum)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
|---|---|---|---|---|---|---|
| Dr | 5220002 | Cash at bank | 175,000 | 175,000 | 175,000 | 175,000 |
| Cr | 5232103 | Other loans and advances - Repayments | 175,000 | 175,000 | 175,000 | 175,000 |
Table A.2.4.2: Recognition of the unwinding of the discount (Table A.2.4 column ‘(d)’)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
|---|---|---|---|---|---|---|
| Dr | 5232104 | Other loans and advances – Non cash movements | 41,493 | 32,148 | 22,148 | 11,449 |
| Cr | 1234001 | Unwind concessional loan discount (income) | 41,493 | 32,148 | 22,148 | 11,449 |
Table A.2.4.3: Recognition of the annual adjustment to expected credit loss allowance
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
|---|---|---|---|---|---|---|
| Dr | 5233023 | Provision for Doubtful Debts - Other | 18,000 | 20,000 | 8,000 | 4,000 |
| Cr | 2251004 | Loans and Advances Bad Doubtful Debts | 18,000 | 20,000 | 8,000 | 4,000 |
A.3 – Below market-rate loan with grace period, credit risks increased since initial recognition
Scenario
On 1 July 20X0, the lending entity agrees to provide a loan with the following terms:
- Principal: $700,000
- Term: 6 years with a grace period of no principal repayments for first 2 years
- Loan interest rate: 3.45 per cent per annum
- Repayments: to be repaid in four equal instalments ($175,000 per annum) from 20X2-X3 onwards (Year 3 to Year 6).
Other factors/considerations:
- Loan documents: signed at the date of the loan funds being provided
- Market-rate: if the loan was borrowed in the market place, an interest rate of 7.45 per cent per annum would have applied
- Transaction costs: no transaction costs directly attributable to the issue of the concessional loan were incurred
- Loan interest: calculated on the amount outstanding at the beginning of the year and payable annually. Cash flows occur at year-end.
- Credit risks: in June 20X1 (end of year 1), credit risks were assessed to have significantly increased since initial recognition.
Expected credit losses were estimated in July 20X0 (beginning of year 1) based on the probability of credit default occurring in the next 12 months, and at the beginning of years 20X1-X2 to 20X5-X6 based on the probability of lifetime credit default (shown in Table A.3.1.)
Table A.3.1: Expected credit loss allowance (ECLA)
| Year | Principal outstanding | Expected credit loss allowance |
|---|---|---|
| July 20X0 | $700,000 | $50,00016 |
| July 20X1 | $700,000 | $65,000 |
| July 20X2 | $700,000 | $60,000 |
| July 20X3 | $525,000 | $36,000 |
| July 20X4 | $350,000 | $14,000 |
| July 20X5 | $175,000 | $5,000 |
16 The calculation of ECLA is shown at Appendix B.
Accounting guidance
Concessional loan (A) = market based loan (B) + loan discount (C)
As per previous examples, the loan (A) is classified as a financial asset held at ‘amortised cost’ and no loan commitment needs to be initially recognised. The loan is separated into a market-based loan (B) and the loan discount (C).
Discounted cash flow analysis
The market-based loan is recognised at fair value using DCF analysis. The market discount rate is still 7.45 per cent per annum.
The PV of the future cash flows at the market rate for and at the concessional rate of 3.45 per cent per annum for are illustrated in Table A.3.2.
Table A.3.2: Discounted cash flow analysis
| Year | Principal repayment | Interest payment at loan rate (3.45%) | Total cash flows |
PV at loan rate (A) |
PV at market rate (7.45%) (B) |
|---|---|---|---|---|---|
| 20X0-X1 | $- | $24,150 (700,000 x 0.0345) |
$24,150 | $23,345 (24,150 / (1.0345)1) |
$22,476 (24,150 / (1.0745)1) |
| 20X1-X2 | $- | $24,150 (700,000 x 0.0345) |
$24,150 | $22,566 (24,150 / (1.0345)2) |
$20,917 (24,150 / (1.0745)2) |
| 20X2-X3 | $175,000 | $24,150 (700,000 x 0.0345) |
$199,150 | $179,882 (199,150 / (1.0345)3) |
$160,532 (199,150 / (1.0745)3) |
| 20X3-X4 | $175,000 | $18,113 (525,000 x 0.0345) |
$193,113 | $168,612 (193,113 / (1.0345)4) |
$144,872 (193,113 / (1.0745)4) |
| 20X4-X5 | $175,000 | $12,075 (350,000 x 0.0345) |
$187,075 | $157,893 (187,075 / (1.0345)5) |
$130,612 (187,075 / (1.0745)5) |
| 20X5-X6 | $175,000 | $6,038 (175,000 x 0.0345) |
$181,038 | $147,702 (181,038 / (1.0345)6) |
$117,633 (181,038 / (1.0745)6) |
| Total | $700,000 | $108,676 | $808,676 | $700,000 | $597,042 |
Calculating loan discount
In this scenario, the difference between the interest free loan (A) and market-based loan (B) (before transaction costs) represents the discount implicit in the loan (C).
Concessional loan (A) - market-based loan (B) = loan discount (C)
From Table A.3.2:
(Total column A) $700,000 – (Total column B) $597,042 = Loan discount (C) $102,958
Journal entries
At 1 July 20X0, the entity posts the following journal to recognise the:
- fair value of the market-based loan component and to expense the associated loan discount component
- an initial ECLA.
Table A3.2.1: Recognition of the concessional loan in July 20X0
| Dr/Cr | CBMS Account | CBMS Account Description | Amount |
|---|---|---|---|
| Dr | 2423001 | Concessional loan discount (expense) | $102,958 |
| Dr | 5232102 | Other loans and advances – Advances and loans made | $700,000 |
| Cr | 5232104 | Other loans and advances – Non cash movements | $102,958 |
| Cr | 5220002 | Cash at bank | $700,000 |
Table A.3.2.2: Recognition of ECLA
| Dr/Cr | CBMS Account | CBMS Account Description | Amount |
|---|---|---|---|
| Dr | 2251004 | Loans and Advances Bad Doubtful Debts | $50,000 |
| Cr | 5233023 | Provision for Doubtful Debts - Other | $50,000 |
Amortisation schedule – market-based loan
The following schedule outlines the amortisation of the market-based loan, and illustrates how the EIM effectively discounts estimated future principal and interest receipts through the expected life of the loan:
Table A.3.3: Amortisation schedule – market-based loan
|
Year |
(a) Opening Gross Carrying Amount |
(b) = (a) x EIR Income (using EIM) |
(c) Cash flows17 |
(d) = (a) + (b) – (c) Closing Gross Carrying Amount |
|---|---|---|---|---|
| 20X0-X1 | $597,04218 | $44,480 | $24,150 | $617,372 |
| 20X1-X2 | $617,372 | $45,994 | $24,150 | $639,216 |
| 20X2-X3 | $639,216 | $47,622 | $199,150 | $487,688 |
| 20X3-X4 | $487,688 | $36,333 | $193,113 | $330,908 |
| 20X4-X5 | $330,908 | $24,653 | $187,075 | $168,486 |
| 20X5-X6 | $168,486 | $12,552 | $181,038 | $- |
17 Cash flows from Table A.3.2: Discounted cash flow analysis
18 The total for (B) in Table A.3.2: Discounted cash flow analysis
Calculation of unwinding of discount and unexpired discount
The following table illustrates the unwinding of the loan discount (noting that there may be discrepancies in totals due to interest rate rounding):
Table A.3.4: Calculation of unwinding of discount and unexpired discount
|
Year |
(a) Opening loan discount |
(b) Income (using EIM)19 |
(c) Interest income20 |
(d) = (b) – (c) Income from unwinding of discount |
(e) = (a) – (d) Unexpired loan discount at year end |
|---|---|---|---|---|---|
| 20X0-X1 | $102,958 | $44,480 | $24,150 | $20,330 | $82,628 |
| 20X1-X2 | $82,628 | $45,994 | $24,150 | $21,844 | $60,784 |
| 20X2-X3 | $60,784 | $47,622 | $24,150 | $23,472 | $37,312 |
| 20X3-X4 | $37,312 | $36,333 | $18,113 | $18,220 | $19,092 |
| 20X4-X5 | $19,092 | $24,653 | $12,075 | $12,578 | $6,514 |
| 20X5-X6 | $6,514 | $12,552 | $6,038 | $6,514 | $- |
| Total | $211,634 | $108,676 | $102,958 |
19 Income from column ‘(b)’ in Table A.3.3: Amortisation Schedule
20 Interest payments from Table A.3.2: Discounted cash flow analysis
Subsequent accounting
The lending entity posts the following journals at the end of each financial year:
Table A.3.4.1: Recognition of principal repayments ($175,000 per annum)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
30/06/X5 $ |
30/06/X6 $ |
|---|---|---|---|---|---|---|---|---|
| Dr | 5220002 | Cash at bank | - | - | 175,000 | 175,000 | 175,000 | 175,000 |
| Cr | 5232103 | Other loans and advances - Repayments | - | - | 175,000 | 175,000 | 175,000 | 175,000 |
Table A.3.4.2: Recognition of interest income (Table A.3.4 column c)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
30/06/X5 $ |
30/06/X6 $ |
|---|---|---|---|---|---|---|---|---|
| Dr | 5220002 | Cash at bank | 24,150 | 24,150 | 24,150 | 18,113 | 12,075 | 6,038 |
| Cr | 1232005 | Interest from loans and advances | 24,150 | 24,150 | 24,150 | 18,113 | 12,075 | 6,038 |
Table A.3.4.3: Recognition of the unwinding of the discount (Table A.3.4 column d))
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
30/06/X5 $ |
30/06/X6 $ |
|---|---|---|---|---|---|---|---|---|
| Dr | 5232104 | Other loans and advances – Non cash movements |
20,330
|
21,844
|
23,472
|
18,220
|
12,578
|
6,514
|
| Cr | 1234001 | Unwind concessional loan discount (income) |
20,330
|
21,844
|
23,472
|
18,220
|
12,578
|
6,514
|
Table A.3.4.4: Recognition of the annual adjustment to expected credit loss allowance
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
30/06/X5 $ |
30/06/X6 $ |
|---|---|---|---|---|---|---|---|---|
| Dr | 5233023 | Provision for doubtful debts – other |
-15,000
|
5,000
|
24,000
|
22,000
|
9,000
|
5,000
|
| Cr | 2251004 | Loans and Advances Bad Doubtful Debts |
-15,000
|
5,000
|
24,000
|
22,000
|
9,000
|
5,000
|
A.4 – Interest-free loan with grace period
Scenario
On 1 July 20X0, the lending entity agrees to provide a loan on the following terms:
- Principal: $700,000
- Term: 6 years, with a grace period of no principal repayments in the first 2 years for 20X0-X1 and 20X1-X2
- Loan interest rate: interest free
- Repayments: to be repaid evenly over the loan term ($175,000 per annum).
Other factors/considerations:
- Loan documents: signed at the date of the loan funds being provided
- Market-rate: if the loan was borrowed in the market place, an interest rate of 7.45 per cent per annum would have applied
- Transaction costs: no transaction costs directly attributable to the issue of the concessional loan were incurred.
- Credit risk: Over the life of the loan, credit risks were assessed to have not significantly increased since the financial asset’s initial recognition. Expected credit losses were therefore estimated at the beginning of each financial year based on the probability of credit default occurring in the next 12 months.
Table A.4.1: Expected credit loss allowance
|
Year
|
Principal outstanding | Estimated probability of default (next 12 months) |
Estimated present value of LGD | Expected credit loss allowance21 |
|---|---|---|---|---|
| July 20X0 | $700,000 | 10% | $500,000 | $50,000 |
| July 20X1 | $700,000 | 10% | $500,000 | $50,000 |
| July 20X2 | $700,000 | 10% | $500,000 | $50,000 |
| July 20X3 | $525,000 | 9% | $400,000 | $36,000 |
| July 20X4 | $350,000 | 7% | $200,000 | $14,000 |
| July 20X5 | $175,000 | 5% | $100,000 | $5,000 |
21 The calculation of ECLA is shown at Appendix B.
Accounting guidance
Concessional loan (A) = market based loan (B) + loan discount (C)
The loan (A) is classified as a financial asset held at ‘amortised cost’ and no loan commitment needs to be initially recognised. The loan is separated into a market-based loan (B) and the loan discount (C).
Discounted cash flow analysis
The market-based loan is recognised at fair value using DCF analysis.
The PV of the future cash flows at the market rate for and at the concessional rate of
0 per cent for (A) are illustrated in Table A.4.2.
Table A.4.2: Discounted cash flow analysis
| Year | Principal repayment | Interest payment at loan rate (0%) | Total cash flows | PV at loan rate (0%) (A) |
PV at market rate (7.45%) (B) |
|---|---|---|---|---|---|
| 20X0-X1 | $- | $- | $- | $- | $- |
| 20X1-X2 | $- | $- | $- | $- | $- |
| 20X2-X3 | $175,000 | $- | $175,000 | $175,000 (175,000 /(1.0000)3) |
$141,065 (175,000 /(1.0745)3) |
| 20X3-X4 | $175,000 | $- | $175,000 | $175,000 (175,000 /(1.0000)4) |
$131,284 (175,000 /(1.0745)4) |
| 20X4-X5 | $175,000 | $- | $175,000 | $175,000 (175,000 /(1.0000)5) |
$122,182 (175,000 /(1.0745)5) |
| 20X5-X6 | $175,000 | $- | $175,000 | $175,000 (175,000 /(1.0000)6) |
$113,710 (175,000 /(1.0745)6) |
| Total | $700,000 | $- | $700,000 | $700,000 | $508,241 |
Calculating loan discount
In this scenario, the difference between the concessional (interest free) loan (A) and a market-based loan (B).
Concessional loan (A) - market-based loan (B) = loan discount (C)
From Table A.4.2:
(Total column A) $700,000 – (Total column B) $508,241 = Loan discount (C) $191,759
Journal entries
At 1 July 20X0, the entity posts the following journal to recognise:
- fair value of the market-based loan component and to expense the associated loan discount component
- an initial ECLA
Table A.4.2.1: Recognition of concessional loan
| Dr/Cr | CBMS account | CBMS account description | Amount |
|---|---|---|---|
| Dr | 2423001 | Concessional loan discount (expense) | $191,759 |
| Dr | 5232102 | Other loans and advances – Advances and loans made | $700,000 |
| Cr | 5232104 | Other loans and advances – Non cash movements | $191,759 |
| Cr | 5220002 | Cash at bank | $700,000 |
Table A.4.2.1: Recognition of ECLA
| Dr/Cr | CBMS account | CBMS account description | Amount |
|---|---|---|---|
| Dr | 2251004 | Loans and Advances Bad Doubtful Debts | $50,000 |
| Cr | 5233023 | Provision for Doubtful Debts - Other | $50,000 |
Amortisation schedule – market-based loan
The following amortisation schedule outlines the amortisation of the market-based loan:
Table A.4.3: Amortisation schedule – market-based loan
|
Year |
(a) Opening gross carrying amount |
(b) = (a) x EIR Income (using EIM) |
(c) Cash flows22 |
(d) = (a) + (b) – (c) Closing gross |
|---|---|---|---|---|
| 20X0-X1 | $508,24123 | $37,864 | $- | $546,105 |
| 20X1-X2 | $546,105 | $40,685 | $- | $586,790 |
| 20X2-X3 | $586,790 | $43,715 | $175,000 | $455,505 |
| 20X3-X4 | $455,505 | $33,935 | $175,000 | $314,440 |
| 20X4-X5 | $314,440 | $23,426 | $175,000 | $162,866 |
| 20X5-X6 | $162,866 | $12,134 | $175,000 | $- |
22 Cash flows are from Table A.4.2: Discounted cash flow analysis
23 The total for (B) in Table A.4.2: Discounted cash flow analysis.
Calculation of unwinding of discount and unexpired discount
The following table illustrates the unwinding of the loan discount.
Table A.4.4: Calculation of unwinding of discount and unexpired discount
|
Year |
(a) Opening |
(b) Income |
(c) Interest |
(d) = (b) – (c) Income |
(e) = (a) – (d) Unexpired |
|---|---|---|---|---|---|
| 20X0-X1 | $191,75926 | $37,864 | $- | $37,864 | $153,895 |
| 20X1-X2 | $153,895 | $40,685 | $- | $40,685 | $113,210 |
| 20X2-X3 | $113,210 | $43,715 | $- | $43,715 | $69,495 |
| 20X3-X4 | $69,495 | $33,935 | $- | $33,935 | $35,560 |
| 20X4-X5 | $35,560 | $23,426 | $- | $23,426 | $12,134 |
| 20X5-X6 | $12,134 | $12,134 | $- | $12,134 | $- |
| Total | $- | $191,759 |
24 Income from column ‘(b)’ in Table A.4.3: Amortisation Schedule.
25 Interest payments from Table A.4.2: Discounted cash flow analysis
26 As calculated using the ‘loan discount’ formula.
Subsequent accounting
The lending entity posts the journals at the end of each financial year:
Table A.4.4.1: Recognition of principal repayments ($175,000 per annum)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
30/06/X5 $ |
30/06/X6 $ |
|---|---|---|---|---|---|---|---|---|
| Dr | 5220002 | Cash at bank | - | - | 175,000 | 175,000 | 175,000 | 175,000 |
| Cr | 5232103 | Other loans and advances - Repayments | - | - | 175,000 | 175,000 | 175,000 | 175,000 |
Table A.4.4.2: Recognition of the unwinding of the discount (Table A.4.3 column (b))
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
30/06/X5 $ |
30/06/X6 $ |
|---|---|---|---|---|---|---|---|---|
| Dr | 5232104 | Other loans and advances – Non cash movements | 37,864 | 40,685 | 43,715 | 33,935 | 23,426 | 12,134 |
| Cr | 1234001 | Unwind concessional loan discount (income) | 37,864 | 40,685 | 43,715 | 33,935 | 23,426 | 12,134 |
Table A.4.4.3: Recognition of the annual adjustment to expected credit loss allowance
| Dr/Cr | CBMS account |
CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
30/06/X5 $ |
30/06/X6 $ |
|---|---|---|---|---|---|---|---|---|
| Dr | 5233023 | Provision for doubtful debts – other | - | - | 14,000 | 22,000 |
9,000
|
5,000
|
| Cr | 2251004 | Loans and Advances Bad Doubtful Debts | - | - | 14,000 | 22,000 |
9,000
|
5,000
|
A.5 – Interest-free loan which becomes credit impaired
Scenario
On 1 July 20X0, the lending entity agrees to provide an interest-free loan. In year 20X1-X2, the lending entity assessed that the loans credit risks had significantly increased since initial recognition. In year 20X2-X3, the loan was assessed as credit impaired. In year 20X3-X4, the borrower was declared bankrupt and the outstanding loan was written off.
The terms for the loan are as follows:
- Principal: $700,000
- Term: 4 Years
- Loan interest rate: interest free
- Repayments: to be repaid evenly over the loan term ($175,000 per annum).
Other factors/considerations:
- Loan documents signed: at the date of the loan funds being provided
- Market-rate: if the loan was borrowed commercially an interest rate of 7.45 per cent per annum would have applied
- Transaction costs: no transaction costs directly attributable to the issue of the concessional loan were incurred
- Credit risk: In year 20X1-X2, credit risks were assessed to have significantly increased since the financial asset’s initial recognition. In year 20X2-X3, the loan was assessed as credit impaired. In year 20X3-X4, the borrower was declared bankrupt and the outstanding loan was written off. Expected credit losses were estimated in July 20X0 based on the probability of credit default occurring in the next 12 months. From 20X1-X2 to 20X3-X4, expected credit losses were estimated based on the probability of credit default occurring over the life of the loan.
Table A.5.1: Expected credit loss allowance
| Year | Principal outstanding | Expected credit loss allowance |
|---|---|---|
| July 20X0 | $700,000 | $50,000 27 |
| July 20X1 | $525,000 | $80,000 |
| July 20X2 | $350,000 | $120,000 |
| July 20X3 | $350,000 | $180,000 |
27 The calculation of ECLA is shown at Appendix B.
Accounting guidance
As per the other Illustrative examples, the loan (A) is classified as a financial asset held at ‘amortised cost’ and no loan commitment needs to be initially recognised.
The loan is separated into a market-based loan (B) and the loan discount (C).
Concessional loan (A) = market based loan (B) + loan discount (C)
Discounted cash flow analysis
The market-based loan is recognised at fair value using DCF analysis.
Table A.5.2 illustrates the PV of the future cash flows at the market rate for (B) and at the concessional rate of 0 per cent for (A).
Table A.5.2: Discounted cash flow analysis
|
Year |
Principal repayment |
Interest payment at loan rate (0%) |
Total cash flows |
(A) PV at loan rate |
(B) PV at market rate (7.45%) |
|---|---|---|---|---|---|
| 20X0-X1 | $175,000 | $- | $175,000 | $175,000 (175,000 / (1.0000)1) |
$162,866 (175,000 / (1.0745)1) |
| 20X1-X2 | $175,000 | $- | $175,000 | $175,000 (175,000 / (1.0000)2) |
$151,574 (175,000 / (1.0745)2) |
| 20X2-X3 | $175,000 | $- | $175,000 | $175,000 (175,000 / (1.0000)3) |
$141,065 (175,000 / (1.0745)3) |
| 20X3-X4 | $175,000 | $- | $175,000 | $175,000 (175,000 / (1.0000)4) |
$131,284 (175,000 / (1.0745)4) |
| Total | $700,000 | $- | $700,000 | $700,000 | $586,789 |
Calculating loan discount
In this scenario, the difference between the concessional (interest free) loan (A) and a market-based loan (B) is:
Concessional loan (A) - market-based loan (B) = loan discount (C)
From Table A.5.2:
(Total column A) $700,000 – (Total column B) $586,789 = Loan discount (C) $113,211
Journal entries
At 1 July 20X0, the lending entity posts the following journals to recognise:
- fair value of the market-based loan component and to expense the associated loan discount component
- an initial ECLA.
Table A.5.2.1: Recognition of the concessional loan at 1 July 20X0
| Dr/Cr | CBMS account | CBMS account description | Amount |
|---|---|---|---|
| Dr | 2423001 | Concessional loan discount (expense) | $113,211 |
| Dr | 5232102 | Other loans and advances - Advances and loans made | $700,000 |
| Cr | 5232104 | Other loans and advances – Non cash movements | $113,211 |
| Cr | 5220002 | Cash at bank | $700,000 |
Table A.5.2.2: Recognition of ECLA
| Dr/Cr | CBMS account | CBMS account description | Amount |
|---|---|---|---|
| Dr | 2251004 | Loans and Advances Bad Doubtful Debts | $50,000 |
| Cr | 5233023 | Provision for Doubtful Debts – Other | $50,000 |
Amortisation schedule – market-based loan
The following amortisation schedule outlines the planned amortisation of the loan:
Table A.5.3: Amortisation schedule – market-based loan (as at July 20X0)
|
Year |
(a) Opening gross carrying amount |
(b) = (a) x EIR Income (using EIM) |
(c) Cash flows28 |
(d) = (a) + (b) – (c) Closing gross |
|---|---|---|---|---|
| 20X0-X1 | $586,78929 | $43,716 | $175,000 | $455,505 |
| 20X1-X2 | $455,505 | $33,935 | $175,000 | $314,440 |
| 20X2-X3 | $314,440 | $23,426 | $175,000 | $162,866 |
| 20X3-X4 | $162,866 | $12,134 | $175,000 | $- |
28 Cash flows are from Table A.5.2: Discounted cash flow analysis
29 The total for (B) in Table A.5.2: Discounted cash flow analysis
Calculation of unwinding of discount and unexpired discount
The following table schedules the planned unwinding of the loan discount:
Table A.5.4: Calculation of unwinding of discount and unexpired discount (as at July 20X0)
|
Year |
(a) Opening loan discount |
(b) Income |
(c) Interest |
(d) = (b) – (c) Income from unwinding |
(e) = (a) – (d) Unexpired |
|---|---|---|---|---|---|
| 20X0-X1 | $113,211 | $43,716 | $- | $43,716 | $69,495 |
| 20X1-X2 | $69,495 | $33,935 | $- | $33,935 | $35,560 |
| 20X2-X3 | $35,560 | $23,426 | $- | $23,426 | $12,134 |
| 20X3-X4 | $12,134 | $12,134 | $- | $12,134 | $- |
| Total | $- | $113,211 |
30 Income from column ‘(b)’ in Table A.5.3: Amortisation Schedule.
Subsequent accounting
The lending entity posts the following journals at the end of each financial year:
Table A.5.4.1: Recognition of principal repayments ($175,000 per annum)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
|---|---|---|---|---|---|---|
| Dr | 5220002 | Cash at bank | 175,000 | 175,000 | 0 | 0 |
| Cr | 5232103 | Other loans and advances - Repayments | 175,000 | 175,000 | 0[31] | 0 |
31 Principal repayments were only received in 20X0-X1 and 20X1-X2. Default in repayments occurred in 20X2-X3.
Table A.5.4.2: Recognition of the unwinding of the discount (Table 3 column ‘(d)’)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
|---|---|---|---|---|---|---|
| Dr | 5232104 | Other loans and advances – Non cash movements | 43,716 | 33,935 | 14,486 | 0 |
| Cr | 1234001 | Unwind concessional loan discount (income) | 43,716 | 33,935 | 14,48632 | 0 |
32 Unwinding of the concessional loan expense in 20X2-X3 and 20X3-X4 differs from the planned schedule in Tables 2 and 3. This is because once the loan is assessed as credit impaired, the EIR is applied to the amortised cost of the loan (after deducting ECLA) rather than the loan’s gross carrying value (before ECLA). Unwinding revenue in 20X2-X3 of $14,486 was calculated as 7.45 per cent per annum EIR applied to amortised cost of loan of $194,440 (gross carrying value of loan of $314,440 less revised ECLA as at beginning of 20X2-X3 of $120,000).
Table A.5.4.3: Recognition of annual adjustment to ECLA
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
|---|---|---|---|---|---|---|
| Dr | 2251004 | Loans and Advances Bad Doubtful Debts | 30,000 | 40,000 | 60,000 | 148,92633 |
| Cr | 5233023 | Provision for Doubtful Debts - Other | 30,000 | 40,000 | 60,000 | 148,926 |
33 Amortised cost of loan as at July 20X2 of $194,440 less further increase in ECLA in 20X2-X3 of $60,000 plus unwinding of concessional loan expense of $14,486 in 20X2-X3.
Debt write off
At the end of Year 4, the loan is written off. The balance of the ECLA is increased to $328,926 and then reversed against the asset. Unilateral debt write offs are treated as ‘Other Economic Flows’ for GFS purposes and therefore have no impact on fiscal balance.
Table A.5.4.4: Recognition of the write off of the outstanding loan
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X1 $ |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
|---|---|---|---|---|---|---|
| Dr | 5233023 | Provision for Doubtful Debts - Other | 0 | 0 | 0 | 328,926 |
| Cr | 5232104 | Other loans and advances – Non cash movements | 0 | 0 | 0 | 328,926 |
A.6 – Interest-free loan where repayment is income contingent
Scenario
On 1 July 20X0, the lending entity provided a 2-year interest-free concessional loan of $90,000 to the borrowing entity, with loan discount expense of $10,000 at initial recognition (initial fair value of loan estimated to be $80,000). The terms of the loan are as follows:
- Principal: $90,000
- Term: 2 years
- Loan interest rate: interest-free
- Repayment: to be repaid at end of the loan term, contingent on the borrowing entity’s income
- Loan documents: signed the date that the loan funds were provided
- Transaction costs: directly attributable to the issue of the concessional loan were $3,000.
Accounting guidance
Because the loan is contingent on the borrower’s income, it is classified by the lending entity as a financial asset at FVPL.
Journal entries
At initial recognition, the market-based loan component was recognised in the balance sheet and the discount component was expensed with the following journal entries.
Table A.6.1: Recognition of concessional loan in July 20X0
| Dr/Cr | CBMS account | CBMS account description | Amount |
|---|---|---|---|
| Dr | 2423001 | Concessional loan discount (expense) | $10,000 |
| Dr | 5232102 | Other loans and advances – Advances and loans made | $90,000 |
| Dr | 2230098 | Other supplier expenses | $3,000 |
| Cr | 5232104 | Other loans and advances – Non cash movements | $10,000 |
| Cr | 5220002 | Cash at bank | $93,000 |
Reconciliation of expected credit loss allowance
No ECLA is recognised for loans at FVPL. Transaction costs are expensed as they are incurred.
Calculation of unwinding of discount and unexpired discount
Over the next 2 years, the discount expense of $10,000 will need to be unwound to ensure the receivable will equal $90,000 at the end of the loan. If loan interest was received, it would be separately recognised as interest revenue.
Assuming the discount expense is unwound evenly the following journal would be posted at the end of year’s 1 and 2 (for the purposes of this example it’s assumed no credit risk remains at end of loan term and therefore principal outstanding equals fair value).
Table A.6.2: Recognition of unwinding revenue in 20X0-X1 and 20X1-X2
| Dr/Cr | CBMS Account | CBMS Account Description | Amount |
|---|---|---|---|
| Dr | 5232104 | Other loans and advances – Non-cash movements | $5,000 |
| Cr | 1234001 | Unwind concessional loan discount (income) | $5,000 |
At the end of year 2, the discount is fully unwound resulting in the full receivable of $90,000 (the amount to be received from the borrowing entity).
When the loan is repaid the lending entity posts the following journal entries:
Table A.6.3: Recognition of the repayment of the concessional loan in June 20X2
| Dr/Cr | CBMS Account | CBMS Account Description | Amount |
|---|---|---|---|
| Dr | 5220002 | Cash at bank | $90,000 |
| Cr | 5232103 | Other loans and advances - Repayments | $90,000 |
If in year 2, the entity’s profitability falls below the required threshold for payment and the entity cannot repay the loan, the following journal is posted to recognise the write off of the loan.
| Dr/Cr | CBMS Account | CBMS Account Description | Amount |
|---|---|---|---|
| Dr | 2251004 | Loans and Advances Bad Doubtful Debts | $90,000 |
| Cr | 5232104 | Other loans and advances – Non cash movements | $90,000 |
A.7 – Forward-year concessional loan
Scenario
A loan agreement is signed on 1 July 20X0 for the loan to be advanced on 1 July 20X1, on the following terms:
- Principal: $700,000 to be provided
- Term: 4 years commencing 1 July 20X1
- Loan interest rate: 3.45 per cent per annum, calculated on the amount outstanding at the beginning of the year
- Repayments: annually over the loan term ($175,000 per annum).
Other factors/considerations:
- Loan documents: signed on 1 July 20X0
- Market-rate: a commercial borrowing would have been subject to an interest rate of 7.45 per cent per annum
- Transaction costs: no transaction costs directly attributable to the issue of the concessional loan were incurred
- Credit risks: over the life of the loan, credit risks were assessed to have not significantly increased since initial recognition. Expected credit losses were estimated at the beginning of each financial year based on the probability of default occurring in the next 12 months.
Table A.7.1: Expected credit loss allowance
| Year | Principal Outstanding | Expected Credit Loss Allowance |
|---|---|---|
| July 20X1 | $700,000 | $50,00034 |
| July 20X2 | $525,000 | $32,000 |
| July 20X3 | $350,000 | $12,000 |
| July 20X4 | $175,000 | $4,000 |
34 The calculation of ECLA is shown at Appendix B.
Accounting guidance
The entity separates the concessional loan (A) into its component parts:
- a market-based loan (B)
- the discount component (C).
Concessional loan (A) = market based loan (B) + loan discount (C)
Discounted cash flow analysis
A liability is recognised at 1 July 20X0 to reflect the obligation to make the loan at 1 July 20X1.
Table A.7.2: Discounted cash flow analysis (as at 1 July 20X1)
| Year | Principal repayment | Interest payment at loan rate (3.45%) | Total cash flows |
PV at loan rate (3.45%) (A) |
PV at market rate (7.45%) (B) |
|---|---|---|---|---|---|
| 20X1-X2 | $175,000 | $24,150 (700,000 x 0.0345) |
$199,150 | $192,508 (199,150 / (1.0345)1) |
$185,342 (199,150 / (1.0745)1) |
| 20X2-X3 | $175,000 | $18,113 (525,000 x 0.0345) |
$193,113 | $180,447 (193,113 / (1.0345)2) |
$167,263 (193,113 / (1.0745)2) |
| 20X3-X4 | $175,000 | $12,075 (350,000 x 0.0345) |
$187,075 | $168,976 (187,075 / (1.0345)3) |
$150,798 (187,075 / (1.0745)3) |
| 20X4-X5 | $175,000 | $6,038 (175,000 x 0.0345) |
$181,038 | $158,069 (181,038 / (1.0345)4) |
$135,814 (181,038 / (1.0745)4) |
| Total | $700,000 | $60,376 | $760,376 | $700,000 | $639,216 |
Calculating loan discount
The loan commitments’ fair value as at 1 July 20X0 is calculated as $56,570. This is:
- the concessional loan expense as at 1 July 20X1 of $60,784 ($700,000 - $639,216), discounted back to 1 July 20X0 using the EIR of 7.45 per cent.
- This exceeds the present value of the ECLA as at 1 July 20X0 of $46,533 (ECLA as at 1 July 20X1 of $50,000 discounted back to 1 July 20X0 using the EIR of 7.45 per cent).
Journal entries
Table A.7.2.1: Recognition of loan commitment liability at fair value as at 1 July 20X0
| Dr/Cr | CBMS account | CBMS account description | Amount |
|---|---|---|---|
| Dr | 2423001 | Concessional loan discount (expense) | $56,570 |
| Cr | 3395098 | Other Provisions | $56,570 |
Table A.7.2.1: Recognition of unwinding of present value of loan commitment liability as at 30 June 20X1 ($56,570 * 7.45%)
| Dr/Cr | CBMS Account | CBMS Account Description | Amount |
|---|---|---|---|
| Dr | 2423001 | Concessional loan discount (expense) | $4,214 |
| Cr | 3395098 | Other Provisions | $4,214 |
Table A.7.2.2: Recognition of the provision of loan funds on 1 July 20X1
| Dr/Cr | CBMS Account | CBMS Account Description | Amount |
|---|---|---|---|
| Dr | 3395098 | Other Provisions | $60,784 |
| Dr | 5232102 | Other loans and advances – Advances and loans made | $700,000 |
| Cr | 5232104 | Other loans and advances – Non cash movements | $60,784 |
| Cr | 5220002 | Cash at bank | $700,000 |
Table A.7.2.3: Recognition of initial ECLA on 1 July 20X1
| Dr/Cr | CBMS Account | CBMS Account Description | Amount |
|---|---|---|---|
| Dr | 2251004 | Loans and Advances Bad Doubtful Debts | $50,000 |
| Cr | 5233023 | Provision for Doubtful Debts - Other | $50,000 |
Subsequent accounting
The lending entity posts the following journals at the end of each financial year
Table A.7.3.1: Recognition of principal repayments ($175,000 per annum)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
30/06/X5 $ |
|---|---|---|---|---|---|---|
| Dr | 5220002 | Cash at bank | 175,000 | 175,000 | 175,000 | 175,000 |
| Cr | 5232103 | Other loans and advances - Repayments | 175,000 | 175,000 | 175,000 | 175,000 |
Table A.7.3.2: Recognition of interest income (Table A.7.2)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
30/06/X5 $ |
|---|---|---|---|---|---|---|
| Dr | 5220002 | Cash at bank | 24,150 | 18,113 | 12,075 | 6,038 |
| Cr | 1232005 | Interest from loans and advances | 24,150 | 18,113 | 12,075 | 6,038 |
Table A.7.3.3: Recognition of the unwinding of the discount (see for reference Table A.1.4 column ‘(d)’)
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
30/06/X5 $ |
|---|---|---|---|---|---|---|
| Dr | 5232104 | Other loans and advances – Non cash movements | 23,472 | 18,220 | 12,578 | 6,514 |
| Cr | 1234001 | Unwind concessional loan discount (income) | 23,472 | 18,220 | 12,578 | 6,514 |
Table A.7.3.4: Recognition of the annual adjustment to expected credit loss allowance
| Dr/Cr | CBMS Account | CBMS account description |
30/06/X2 $ |
30/06/X3 $ |
30/06/X4 $ |
30/06/X5 $ |
|---|---|---|---|---|---|---|
| Dr | 5233023 | Provision for Doubtful Debts - Other | 18,000 | 20,000 | 8,000 | 4,000 |
| Cr | 2251004 | Loans and Advances Bad Doubtful Debts | 18,000 | 20,000 | 8,000 | 4,000 |
Appendix B: Expected credit loss allowance
Link copiedIn July 20X0, the lending entity estimates the possible cash flows it would receive over the life of the loan, if the borrowing entity defaults in the next 12 months. Estimated cash flows and the probability of each scenario occurring are set out in Table B.1.1.
Table B.1.1: Expected cash flows by default scenarios
| Scenario | Probability of the Scenario | Expected cash flows 20X0-X1 | Expected cash flows 20X1-X2 | Expected cash flows 20X2-X3 | Expected cash flows 20X3-X4 | Total |
|---|---|---|---|---|---|---|
| A | 5% | $0 | $0 | $124,060 | $333,250 | $457,310 |
| B | 8% | $21,500 | $80,800 | $124,060 | $266,600 | $492,960 |
| C | 10.5% | $43,000 | $103,900 | $136,500 | $333,250 | $616,650 |
| D | 76.5% | $199,150 | $193,113 | $187,075 | $181,038 | $760,376 |
Scenario A: liquidation of the borrower
Scenario B: borrower continues under insolvency administration
Scenario C and D: borrower continues operations under unfavourable/favourable industry conditions respectively.
Expected cash flows (FV) for each scenario are then discounted by the original Effective Interest Rate (EIR=7.45%) to determine present value (PV) amount, using the formula:
PV of future cash flows = ∑Cash flows / (1 + effective interest rate) Time period
(where time period is the number of periods.)
The present value for credit risks are shown in Table B.1.2 (note figures are rounded).
Table B.1.2: Present value for credit risk scenarios
Appendix C: Glossary of terms
Link copiedAmortised cost of a financial asset
The amount at which the financial asset is measured at initial recognition minus principal repayments, plus the cumulative amortisation using the effective interest method of any difference between that initial amount and the maturity amount, minus any loss allowance (AASB 9 Appendix A).
Carrying amount
The amount at which an asset is recognised after deducting any accumulated depreciation (amortisation) and accumulated impairment losses thereon.
Concessional loan
A loan provided on more favourable terms than the borrower could obtain in the market place. The concession component may be in the form of lower than market interest rates, longer loan maturity or grace periods before the payment of the principal or interest.
Effective interest method (EIM)
A method of calculating the amortised cost of a financial asset and of allocating the interest income over the relevant period.
Effective interest rate (EIR)
The rate that exactly discounts estimated future cash receipts through the expected life of the financial instrument to the gross carrying amount of the financial instrument.
When calculating the effective interest rate, an entity should estimate cash flows considering all contractual terms of the financial instrument but should not consider expected credit losses. The calculation includes all fees paid or received between parties to the contract that are an integral part of the effective interest rate, transaction costs, and all other premiums or discounts (AASB 9 Appendix A).
Fair value
The price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date (AASB 13 paragraph 9).
Financial asset
Any asset that is:
- cash
- an equity instrument of another entity
- a contractual right:
- to receive cash or another financial asset from another entity
- to exchange financial assets or financial liabilities with another entity under conditions that are potentially favourable to the entity
- a contract that will or may be settled in the entity’s own equity instruments and is:
- a non-derivative for which the entity is or may be obliged to receive a variable number of the entity’s own equity instruments
- a derivative that will or may be settled other than by the exchange of a fixed amount of cash or another financial asset for a fixed number of the entity’s own equity instruments (paragraph 11 of AASB 132 Financial Instruments: Presentation).
Financial asset measured at amortised cost
Is recognised where:
- the financial asset is held within a business model whose objective is to hold financial assets in order to collect contractual cash flows
- the contractual terms of the financial asset give rise on specified dates to cash flows that are solely payments of principal and interest on the principal amount outstanding (AASB 9 paragraph 4.1.2).
Financial asset at fair value through other comprehensive income (FVOCI)
Is recognised where:
- the financial asset is held within a business model whose objective is achieved by both collecting contractual cash flows and selling financial assets
- the contractual terms of the financial asset give rise on specified dates to cash flows that are solely payments of principal and interest on the principal amount outstanding (AASB 9 paragraph 4.1.2A).
Financial asset at fair value through profit or loss (FVPL)
Is recognised where the financial asset does not meet the classification criteria for either ‘held at amortised cost’ or FVOCI (AASB 9 paragraph 4.1.4).
Financial instrument
Any contract that gives rise to a financial asset of one entity and a financial liability or equity instrument of another entity (AASB 132 paragraph 11).
Gross carrying amount of a financial asset
The amortised cost of a financial asset, before adjusting for any loss allowance (AASB 9 Appendix A).
Loan Commitment
A contractual obligation to provide a loan at a future date.