
Disposal
On this page
Entities should regularly review their property portfolio to determine whether each property continues to support service delivery and provide value for money.
Once an entity has determined that a property is surplus to its requirements, it should be listed on the Clearing House to assess whether there is an alternative Australian Government use for the property. The Clearing House only applies to owned properties. Leases that are proposed for termination are not required to be listed.
Entities are not expected to identify all potential alternative uses before listing a property on the Clearing House. If following the Clearing House process, disposal of the property remains the preferred option, a cost-benefit analysis (CBA) should be undertaken to inform the appropriate disposal pathway consistent with legislative and policy requirements and demonstrate value for money.
Legislative and policy requirements
When disposing of property, entities must comply with relevant legislative and policy requirements under the:
- Lands Acquisition Act 1989 (LAA) – disposal of any interest in land is authorised under the LAA.
- Land acquired through a compulsory acquisition process may be subject to additional disposal requirements under the LAA. In certain circumstances, before disposing of land, the Australian Government may be required to offer the land back to the former owner. Section 121 of the LAA sets out the circumstances in which this requirement applies.
- Commonwealth Property Disposal Policy (CPDP) – outlines the criteria to retain ownership and requirements when disposing of property.
Further guidance on disposal requirements under the LAA and the CPDP can be found in RMG 501 Lands Acquisition Framework.
Disposing of property
If a property is considered surplus, it should be progressed for disposal consistent with the CPDP.
The CPDP applies to the disposal of real property. Real property is land and rights or interests attached to the land. The disposal policy is available on the Commonwealth Property Disposal Policy page.
The CPDP requires officials to assess if there is an alternative Australian Government use ahead of disposing outside of the Australian Government. This is done by using the Property Disposal Clearing House – more information is below.
Informed decision-making and value for money
All non-corporate Commonwealth entities (NCEs) must conduct a CBA considering whole-of-life cost (WoLC) for property options, including decisions on whether to own, lease, divest, or transfer Australian Government property. The CBA should consider financial costs and heritage, social, and environmental factors related to the property. Where a formal CBA is completed, entities are required to consult with Finance while conducting the analysis to confirm all relevant factors are included when making value for money decisions.
Should disposal be the relevant option, a disposal strategy should be developed. RMG 501 provides information on what to include in a disposal strategy.
The structure and conditions of all disposals of land suitable for housing are subject to the approval of the Minister for Finance.
For more information on property disposal see RMG 501.
Alternative use proposals
Link copiedAny person or organisation may propose an alternative use for Australian Government land owned by an NCE. Examples of alternative use of land may be to deliver more housing, community amenities, key services or employment hubs.
When an alternative use proposal is received, Finance in conjunction with the owning/occupying entity will undertake an assessment of the landholding. Officials will need to assess the proposal to determine whether the landholdings are surplus to Australian Government requirements.
Officials should take reasonable steps to protect the intellectual property of the proposer as part of their assessment.
An alternative use proposal does not determine the disposal outcome for a property.
Any disposal arising from an alternative use proposal must be consistent with the requirements of the CPDP. While alternative use proposals may inform how a property could be used, the disposal process remains subject to the CPDP. Refer to the CPDP and the Alternative Use Proposal page for further information.
Property Disposal Clearing House
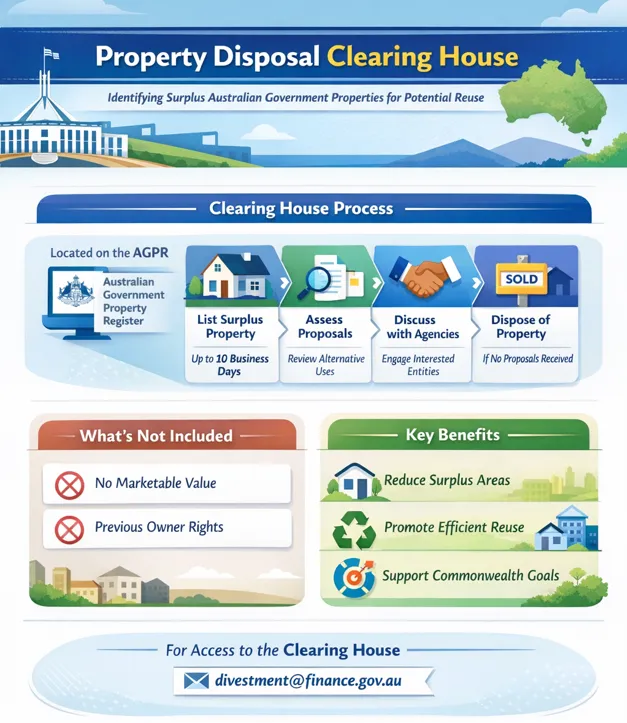
Link copiedThe Clearing House is located on the Australian Government Property Register (AGPR) and applies to all proposed disposals of property, except those with no marketable value or those with previous owner rights.
When determining whether a property is surplus and suitable for listing on the Clearing House, entities should have regard to the surplus property criteria set out in the CPDP. The Clearing House supports officials when assessing whether surplus property can be retained and repurposed within the Australian Government before disposal is considered.
Before proceeding with a disposal, officials must list surplus property on the Clearing House for up to 10 business days. This allows other Australian Government entities the opportunity to propose alternative uses before the property is disposed.
Once this period has passed, the disposing entity will then engage with any entity that has proposed an alternative use to discuss the proposal further. If no proposals are received, officials should proceed with the disposal of the property in accordance with the CPDP.
For access to the Clearing House, contact divestment@finance.gov.au.
Policies, legislation and guidelines
Link copiedResource Management Guides
Link copied- RMG 501 Lands Acquisition Framework
Glossary
Link copied- Accountable Authorities
- Assigning a lease
- Australian Government Property Register (AGPR)
- Budget Process Operational Rules
- Budget Process Operational Rules (BPORs)
- Capital Management Plan (CMP)
- Capital Works
- Chief Financial Officer (CFO)
- Commonwealth authority
- Commonwealth National Lease (CNL)
- Commonwealth Procurement Rules (CPRs)
- Contract Notice (CN)
- Corporate Commonwealth Entities
- Corporate Commonwealth entities (CCEs)
- Cost Benefit Analysis
- Department of Defence (Defence)
- Department of Finance (Finance)
- Detailed Business Case
- Detailed Business Case (DBC)
- Embodied Emissions
- Entity/Entities
- Expediency motion
- Fit-out
- Goods and Services Tax (GST)
- Greenhouse Gas (GHG)
- Greenhouse Gases
- Heads of compensation
- Initial Business Case
- Initial Business Case (IBC)
- Landholder
- Lands Acquisition Act 1989 (LAA)
- Lease
- Lease Endorsement
- Lease Notification
- Leasing Strategy
- Local Impact Assessment
- Memorandum of Understanding
- Memorandum of Understanding (MoU)
- New Policy Proposal
- New Policy Proposal (NPP)
- Non-corporate Commonwealth Entities
- Non-corporate Commonwealth entities (NCEs)
- Occupational Density Target
- Officials
- P50 / P80
- Parliamentary Standing Committee on Public Works
- Parliamentary Standing Committee on Public Works/Public Works Committee (PWC)
- Property
- Property Management Plan (PMP)
- Property Operating Expenses (POE)
- Property Service Provider (PSP)
- Property Services Coordinated Procurement (PSCP)
- Property Services Coordinated Procurement (PSCP) Arrangements
- Public Governance, Performance and Accountability Act 2013 (PGPA Act)
- Public Works
- Public Works Committee Act 1969 (PWC Act)
- Real Property
- Referral motion
- Resource Management Guide (RMG)
- Statistical Area level 2 (SA2)
- Strategic Property Adviser
- Strategic Property Adviser (SPA)
- Surrendering a lease
- Two Stage Capital Works Approval Process
- Value for money
- Whole of Government Leasing Strategy (Leasing strategy)
- Whole-of-Life Costs (WoLC)
- Work Package
- Work-point